I Logged 485 Trades of My Own Gold Robot. 39% of Them Banked Nothing.
Published Aug 9, 2026, 09:32 PM · Updated Sep 28, 2026, 02:58 PM · 6 min read
Most of what gets written about trading robots is written before the testing. This is the opposite: it is what I found after taking my own product apart, including the parts that did not flatter it.
A 90% WIN RATE IS EASIER TO BUILD THAN YOU THINK
Start with the number every gold robot advertises.
I wanted to know what a high win rate is actually worth, so I ran an experiment on my own Expert Advisor. I did not change the entry logic at all. I only shrank the take-profit to 0.2R and widened the stop to six times ATR - the shape of a system that wins small, often, and loses big, rarely.
The result on XAUUSD over 2023 to 2026:
Win rate: 87.1%
Profit factor: 1.00
Net result: approximately zero
An 87% win rate on the first attempt, and it made nothing over three and a half years. I tried other combinations. A 0.3R target with a five-ATR stop gave 81% and profit factor 1.10.
A 0.5R target gave 68% and profit factor 1.00. Every one of them lost money across 2023-2024.
A high win rate on gold is not evidence of an edge. It is a property of where you place the take-profit relative to the stop, and anyone can manufacture it in an afternoon. When you see one advertised, the useful question is not "how often does it win" but "what does it lose when it loses, and how large can that loss be".
These are backtest results, not live trading results.
WHAT THE TRADE LOG SAID ABOUT MY OWN ROBOT
Having established that the headline number was not worth chasing, I went looking for what my own EA was actually doing.
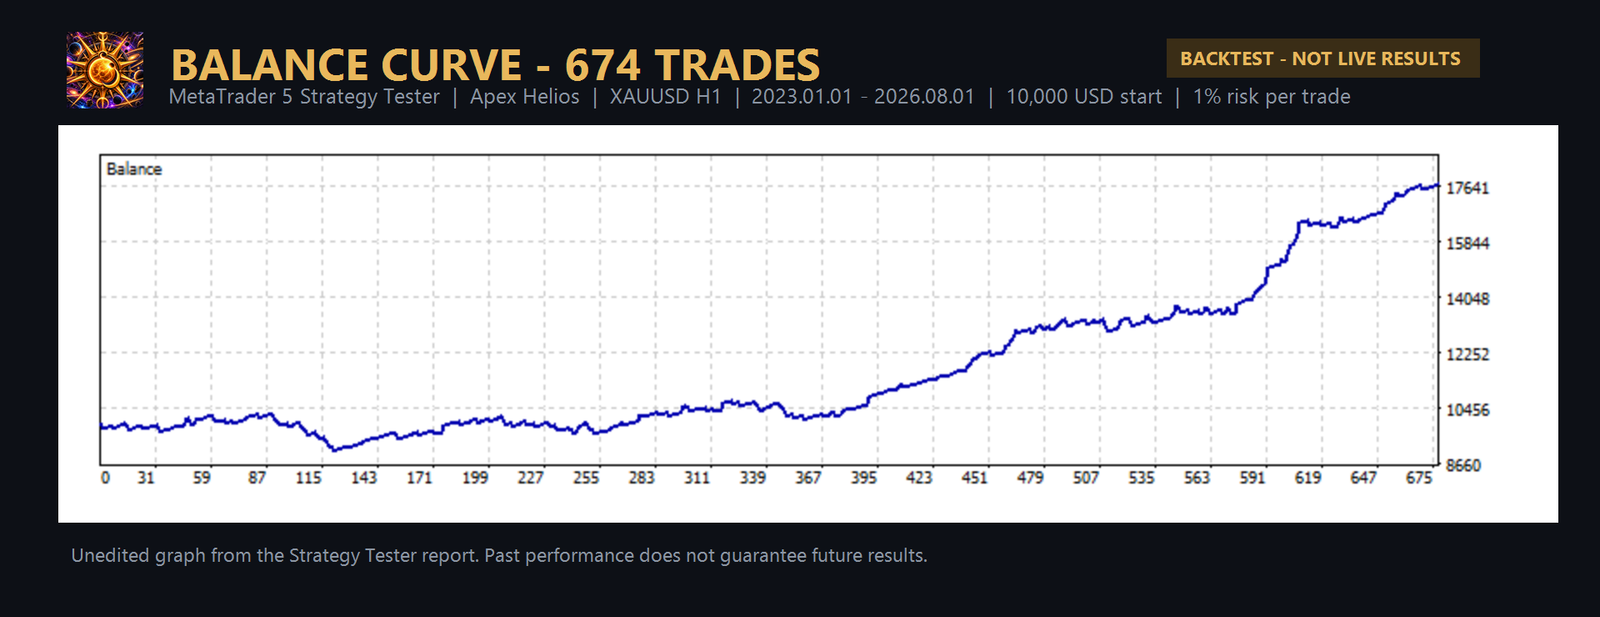
I compiled an instrumented build that wrote a feature vector for every trade - entry hour, day of week, signal type, direction, opening-range size, ATR at entry, risk distance, and the realised result as a multiple of risk. Then I ran it across XAUUSD H1 from January 2023 to August 2026 and looked at the distribution of 485 trades.
Full stop loss (-0.9R or worse): 25.2% of trades
Partial loss: 11.7%
Break-even scratch (within 0.05R): 39.0%
Reached +1R or better: 21.2%
Thirty-nine percent. Two trades in five were doing all the work of a trade - taking the risk, occupying the day, blocking the next setup - and returning nothing.
The mechanism was the break-even stop. The robot pushed to roughly +0.6R, moved its stop to entry, and then gold retraced and took it out flat. It was protecting itself out of its own profits.
Splitting by period made it worse. Across 2023-2024 the system was not profitable at all (profit factor 0.92). Its entire headline result came from the 2025-2026 trend. That is not a strategy, that is a bet on one regime.
THREE CHANGES, EACH TESTED BEFORE IT WAS KEPT
I tuned on 2023-2024 and then checked every change against 2025-2026 data that was not used for tuning. Anything that only improved the half it was fitted to was thrown out.
1. Partial profit taking. If a large share of trades reach partial profit and then retrace, bank some of it. The robot now closes part of the position at a multiple of initial risk and lets the remainder run.
2. A wider target. The winning trades ran far past the old 2R target, so it moved to 4R on gold. I tested 3.5, 4.0, 4.5 and 5.0 - all four improved results. That matters more than the best single value. A setting that works while the settings either side of it fail is an accident, not a discovery.
3. A market-regime filter. The EA now checks daily ADX and stands aside when gold is not trending. This one is direction-agnostic: it asks whether a trend exists, not which way it points. ADX thresholds of 15, 18, 20 and 22 all improved results - another plateau. This change did more to reduce drawdown than anything else.
Combined, across the same data: profit factor moved from 1.21 to 1.68 and maximum drawdown from 21.8% to 11.6%. Both halves of the split sample are now profitable, where the first half previously was not.
WHAT I TESTED AND THREW AWAY
This section is longer than the one above, which is usually how it goes.
A directional daily-EMA trend filter - "only trade with the daily trend" - made both samples worse, taking profit factor from 0.92 to 0.63 in-sample. It removed profitable counter-trend breakouts. This is why the regime filter I kept is direction-agnostic.
Disabling the reversal signals. The trade log suggested they were roughly break-even, so I tried removing them. In-sample results got worse. Kept them.
A hard drawdown halt. This sounds like prudent risk control and it is the opposite. Stopping new trades once equity falls below a threshold locked the account out of its own recovery: 73 trades, profit factor 0.64, a materially worse result than doing nothing. The version I shipped reduces position size while under water instead of halting.
A tight 2% daily loss limit, a 24-bar position timeout, and a tighter cap on opening-range width all made results worse. They ship disabled.
An ADX threshold of 25 looked excellent out-of-sample - profit factor 3.36 - while going negative in-sample. That is the classic overfit trap, and the split sample is the only reason I caught it.
THE FINDING THAT SURPRISED ME MOST
Late in testing I changed one thing that had nothing to do with the strategy: the starting balance. Same settings, same period, same trades.
500 USD: 43.6% maximum drawdown 1,000 USD: 22.7%
2,500 USD: 11.5%
5,000 USD: 11.3%
10,000 USD: 11.6%
Gold's minimum trade size is 0.01 lots, which is one ounce. With a volatility-based stop, that smallest possible position already risks around 40 USD. Percent-risk sizing cannot go below one ounce, so on a small account the real risk per trade is far higher than whatever number you typed into the settings.
The strategy does not change. Only position granularity does. Below roughly 2,500 USD the drawdown profile stops resembling the one in the test report.
I suspect this explains a good share of the disappointed reviews across this whole category.
A buyer funds a small account, follows a "minimum 100 USD" recommendation, watches a 40% drawdown, and concludes the robot is broken. The robot is behaving exactly as designed. The sizing arithmetic was never going to work at that balance.
If you sell trading software, it is worth running your own product at several account sizes before you publish a minimum deposit figure. I had to raise mine considerably.
CLOSING
The version that came out of this is called Apex Helios. It trades one qualified setup per day on XAUUSD H1, takes profit in two stages, stands aside when gold is not trending, and caps the loss on any single trade by solving position size backwards from the stop.
But the part I would rather you take away is the method. Log your trades with their features.
Split your sample and tune on one half only. Check the settings either side of the one you picked. Test your own product at the account size you are recommending.
Past performance does not guarantee future results, and every figure above comes from the Strategy Tester rather than a live account. Test anything you buy on demo with your own broker before you risk money on it - including mine.
Charts and screenshots
Next step
The EA behind these trades is Apex Drawdown Zero; its live results are tracked on real accounts.